 Tyler Durden
Debt Crisis Back? European Bond Markets Crash, CDS Explode Amid France Budget Panic Contagion
It’s starting to smell awful sovereigny crisisy in Europe all over again.
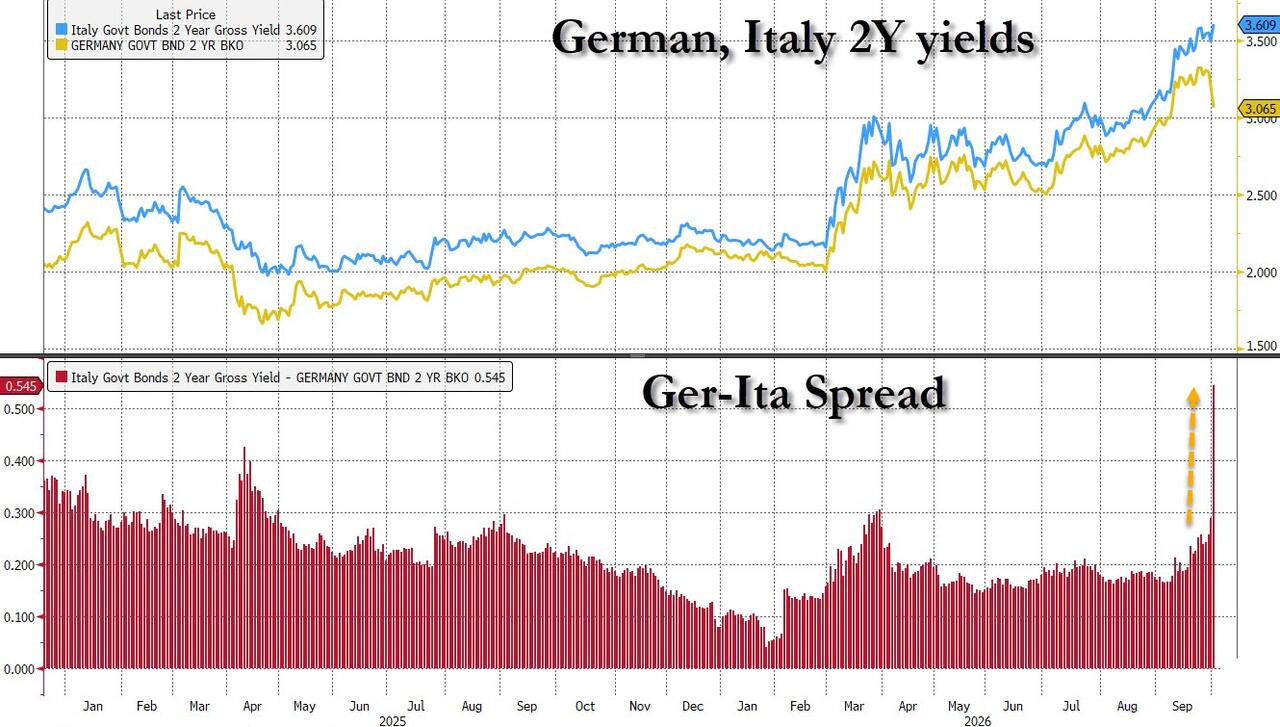
In a vivid deja vu to the peak European debt crisis days of 2010 (and 2011… and 2012… and 2015), credit spreads, credit default swaps and the risk premium in euro-area government bonds exploded on Thursday to levels not seen in over a decade, following a rout sparked by concerns around France’s fiscal and political situation which in addition to local social chaos, is starting to spill over into other markets.
The spread between Italy and Germany’s two-year yields almost doubled to 55 basis points on Thursday, the biggest daily jump since 2020 on a closing basis.
The equivalent gap for France rose as much as 22 basis points, the most since 2012.
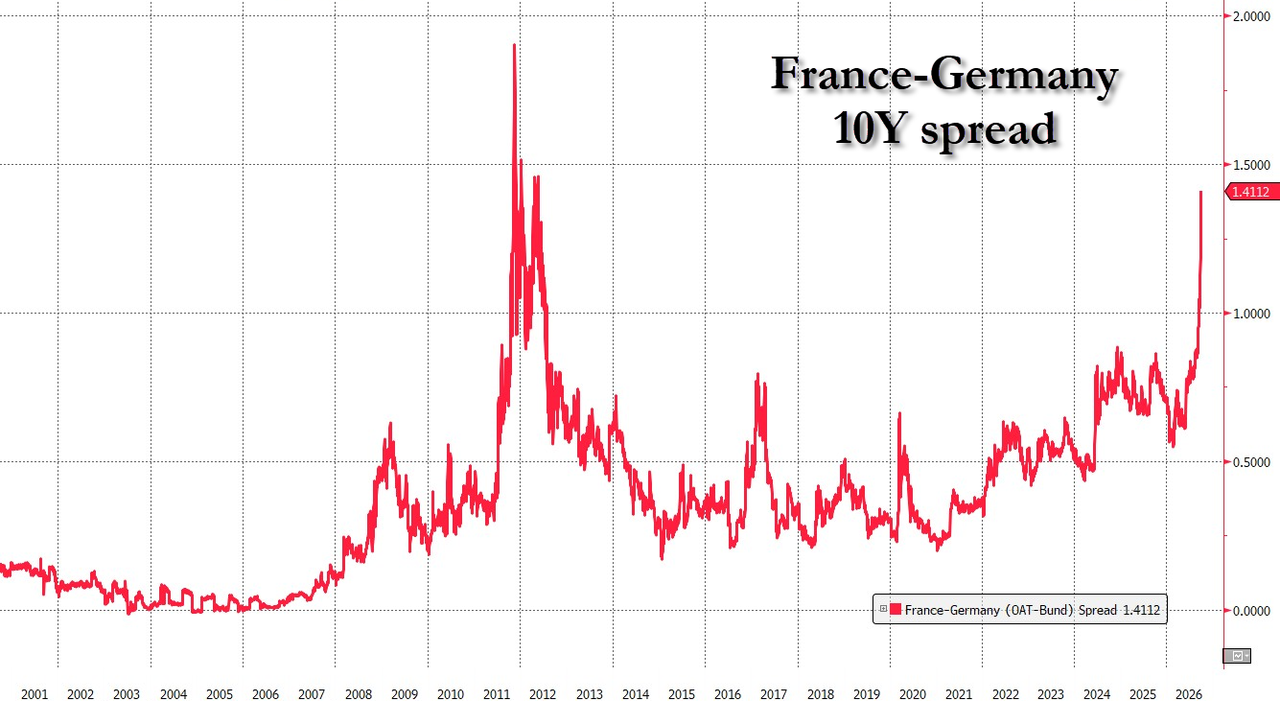
Meanwhile, the spread between 10Y French OATs and 10Y Bunds has soared to 1.41%, the highest going back to the 2012 European Sovereign debt crisis.
A measure of French bond risk reached another milestone this week as investors positioned for political upheaval next year and an ongoing deterioration in the country’s public finances. The widely watched spread between France and Germany’s 10-year yields jumped 14 basis points …
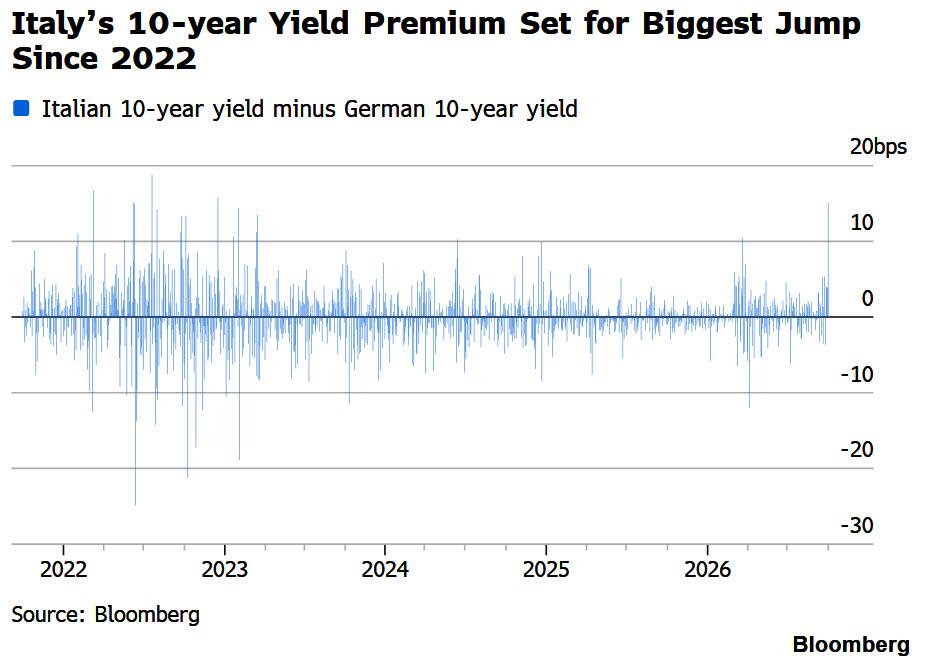
… to 141 basis points, already the widest since 2012.
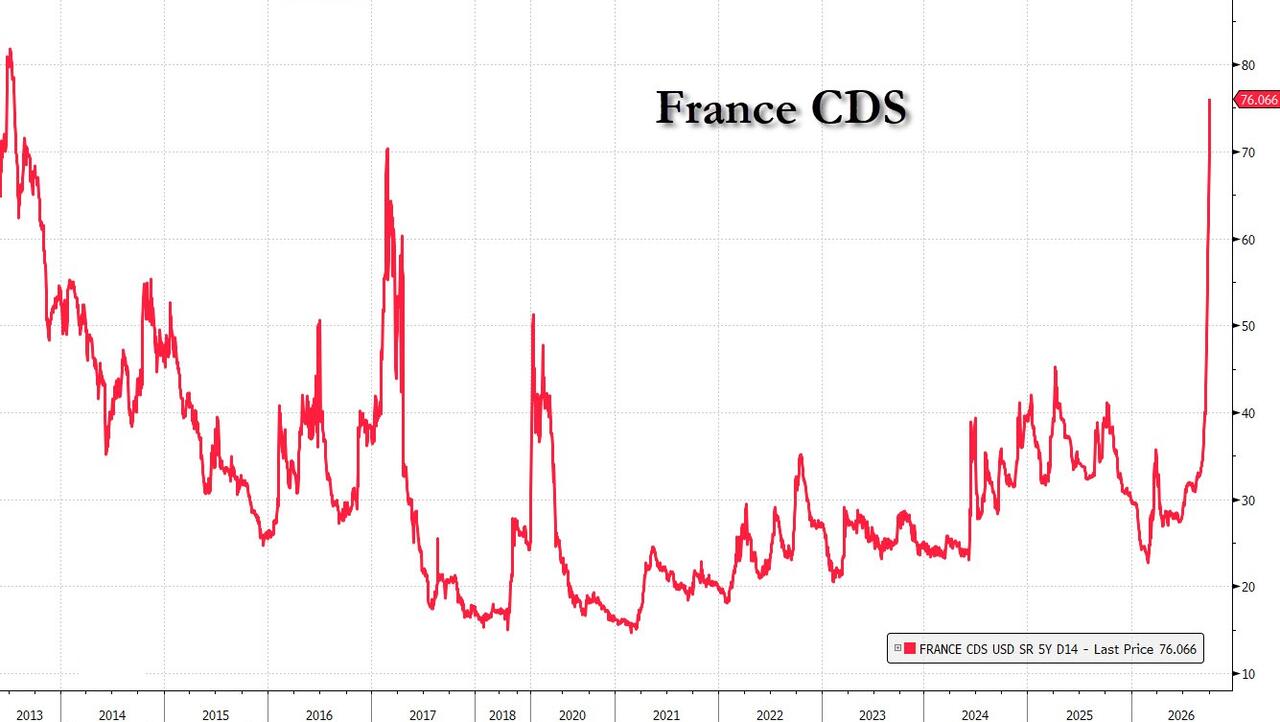
Amid the bond rout, French CDS has more than doubled in the past month on mounting fiscal viability fears.
French credit got monkeyhammered ahead of today’s French budget presentation, which plans to consolidate to a deficit of 5% for next year versus 5.4% expected this. This is how Goldman economist Alex Stott explained it:
“Today is only the formal presentation of the budget. I am not expecting to learn much new relative to the interview Lecornu gave two weeks ago. The more important information will likely be RN’s counter-proposal due next Tuesday, which will give us a sense of the concessions they will ask for in the bill, as well as their plans for the economy if they win the elections. Regarding the budget process, I am expecting it to be very drawn out, potentially lasting until mid-December or early next year. What could accelerate the timeline is if more acute market stress forces political parties to a quicker compromise”
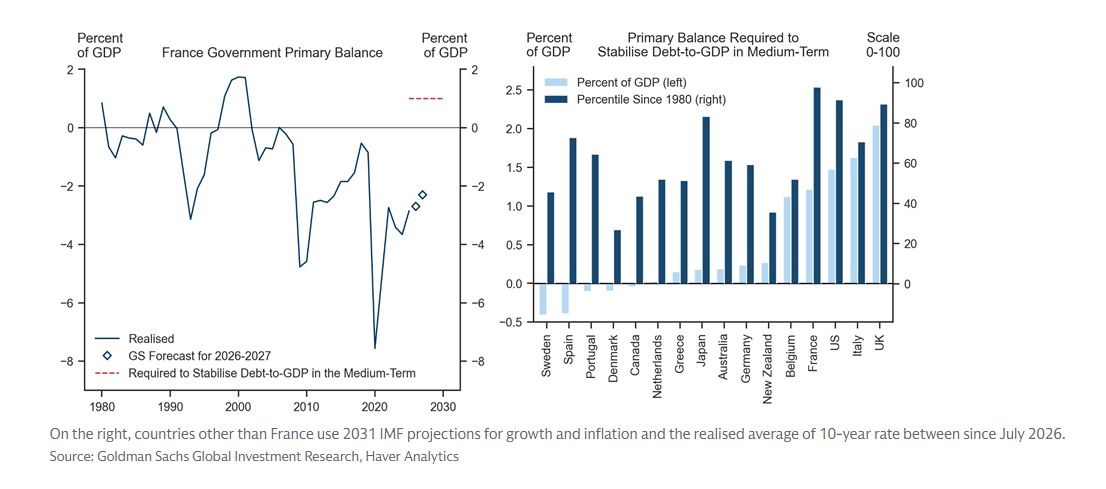
Alex has also modeled France’s medium term debt-GDP path here, which Goldman sees rising to 125% at start of next decade.
In a nutshell, the issue with France is that:
- Average interest rate is set to rise to 3% from 2%
- The primary balance required to stabilise debt is +1% on Goldman’s market forecasts; like many countries but one that France has rarely achieved (95th percentile over past 35 years)
- If you take market rates its even worse; would need to run a 2% primary surplus, something that has never been achieved
- We have elections and policy uncertainty.
As for why the OAT-Bund spread is moving now, some more from Stott:
“past few sessions of spreads widening have not come on the back of any fundamental news. Our current-quarter growth tracking has been pretty stable at 0.1% over the last month, the deficit and budget news were in line with expectations, and polls have been relatively stable too. But clearly have a difficult market backdrop with moves in energy/rates and election uncertainty. Plus would also note discussion around Melenchon’s rise in 1st round polls to second. Though our simulation give him little change of winning in second round (exhibit 7 here: https://tinyurl.com/msm344p9) his proposal to cancel French debt held at Banque de France is the kind of deep tail which can lead to bigger market moves even if his winning probability only shifts slightly”
Today’s violent moves came as German bonds rallied sharply as investors rushed for the region’s “safest” asset (which is ironic for a country whose entire manufacturing sector has been gutted by China), while dumping everything else. Curiously, Treasury yields also surged during the European session, as locals dumped US paper alongside the periphery, although the selloff ended the moment Europe closed.
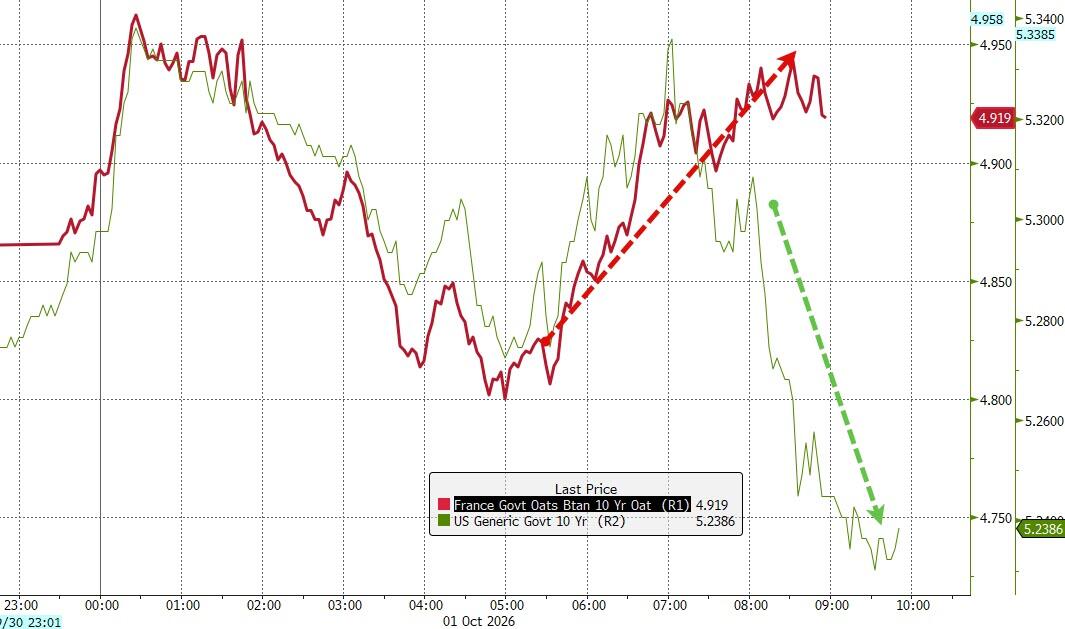
The nervousness suggests the selloff in French markets caused by the nation’s struggle to get a grip on runaway public finances is starting to sap risk appetite more broadly, as we first laid out two months ago in “France’s €107 Billion Deficit Shock: The Next Euro Debt Crisis?“
“France has been slowly but steadily breaking,” said Mike Riddell, lead manager of Fidelity International’s Strategic Bond Fund. “But today feels like the first day that broader financial markets have noticed.”
He’s right:
- ITALY-GERMANY TWO-YEAR BOND YIELD SPREAD WIDENS MOST SINCE 2020
- GERMANY-FRANCE 10Y YIELD SPREAD CLOSES 14BPS WIDER AT 141BPS
There were also signs that markets are starting to price the toll from higher yields – which tighten financial conditions – on the economy. Traders slashed wagers on the extent of further interest-rate hikes from the European Central Bank, and swaps are no longer fully pricing three more quarter-point increases. As recently as Tuesday, they were betting on at least four more.
“The price action is very unusual,” said Rohan Khanna, head of European rates strategy at Barclays. “We are reducing ECB rate hike expectations, yet the EGB complex, with the exception of Germany and the Netherlands, is selling off. It is reminiscent of periods when bond market fragmentation was a major concern, such as during the European sovereign debt crisis.”
In other words, it is reminiscent of when Europe was on the verge – or already in – a debt crisis.
As Bloomberg notes, investors and strategists also said the moves suggested hedge funds have been forced to capitulate on positions as the market moved against them and losses piled up.
“One of the favorite hedge fund carry trades was to own short dated France versus swaps,” added Fidelity’s Riddell. “Some of these positions must have been reduced the past few weeks, but it feels like a capitulation.”
Tyler Durden
Thu, 10/01/2026 – 13:44
ZeroHedge News
[crypto-donation-box type=”tabular” show-coin=”all”]