 Tyler Durden
Confessions Of A Newsletter Writing Market “Permabear”
Submitted by QTR’s Fringe Finance
On my jog yesterday morning I was listening to a podcast about gambling addiction and heard the host bring up the age-old story of a guy selling sports betting picks. The host laughed and asked the obvious question: if this guy is so good at picking winners, why does he need to sell his picks? Why doesn’t he just bet on them himself and get rich?
It’s a fair question, and one I’ve asked about plenty of people over the years. But for whatever reason, after having just finished writing my latest investing dashboard piece, I found myself turning the question around on myself. If I think my analysis of markets and investments is worthwhile, why am I spending my time writing about it instead of simply investing my own money and going about my business?
What exactly am I doing here? Am I really just a “fear monger”? It’s a fair question. Austrian economists have spent decades being accused of peddling doom, predicting catastrophes that never arrive, and frightening people into buying gold or subscribing to newsletters. And frankly, some people have made great livings doing exactly that.
To borrow a term from John Cusack in High Fidelity, am I just part of a “whole sick, sad, miserable subculture” of people who spend their lives obsessing over financial catastrophe, convinced they see something the rest of the world doesn’t?
It’s a fair question. Another fair question is: when does pointing out structural problems become fear mongering, exactly? Is questioning our debt addiction, perpetual deficits, and monetary debasement really selling fear, or simply acknowledging risks most people would rather happily ignore, like that scene in the Matrix where Cypher salivates over being rich and eating steak in a world he knows doesn’t exist?
Or, is the problem simply that I’m not sufficiently huge-brained to appreciate what the intellectual giants peddling Modern Monetary Theory have apparently discovered: that centuries of economic thought, the laws of arithmetic, and everything mankind has ever understood about debt, money, and scarcity have been rendered obsolete because Paul Krugman has given it his blessing? Could this man on the left really represent the pinnacle of the compendium of all human thought about economics?
I suppose the distinction comes down to whether you’re genuinely trying to understand the world or just trying to scare people into paying attention. And I think it’s fair for anyone, including myself, to occasionally ask which side of that line I’m on.
The rest of my run turned into self-examination.
As I wrote back in May in “You Can Never Win, You Can Never Be Right,” I’ve come to accept that I’m not a good trader, but that doesn’t mean I think my analysis is terrible. In fact, I think after a couple of decades of watching markets, working at a public company startup, working with some of the best forensic investigative short sellers in the world and being suspicious of just about everything Wall Street tells me, I’ve developed a reasonably useful way of looking at things.
But, as I explained back in May, I’ve also learned, sometimes at considerable personal expense, that having a decent understanding of what’s happening and making money from that understanding are two different endeavors.
There are a million ways to be right about something and still lose money. You can be right too early, right for the wrong reasons, or right about the big picture while completely misunderstanding the path the market will take to get there. Or my favorite, which is a SuperSized™ kick in the dick (Fig. 1), you can identify an opportunity, buy it, get impatient, sell it, and then watch it do exactly what you thought it would do in the first place.
Few things can make you feel more like s*it than this…
And I’d be lying if I didn’t say I’ve managed to accomplish all of these things, sometimes in remarkably creative fashion.
Over time, I’ve come to realize that I enjoy the intellectual part of investing (pause for laughter) considerably more than I enjoy the mechanics of trading. I like developing ideas, questioning consensus, looking for inconsistencies, and trying to understand the larger forces moving markets. What I don’t particularly enjoy anymore is the psychological circus that comes with trying to turn every observation into a trade.
That’s one reason I am trying to move away from active trading and toward a more permanent, long-term approach to investing. It’s better for both my portfolio and my blood pressure.
I’ve also started to get a much clearer idea of what I actually want to target with the ideas I write about. For years, I’ve been convinced that the United States is eventually going to face some kind of reckoning over its addiction to debt, spending, and monetary intervention. My understanding of Austrian economics has shaped a lot of that thinking, and I still believe that at some point the consequences of decades of financial excess are going to become impossible to ignore. In fact, I think bonds are forcing the issue as you read this. (Read: Bonds Are About To Crash The Stock Market)
But I’ve also resigned to the fact that trying to short the market in anticipation of that outcome is a fool’s errand, at least for me. Governments and central banks have an almost unlimited capacity to come up with new ways to postpone the consequences of their own decisions enough to make nominal prices go higher. Even if my bond thesis is correct, there’s no telling what happens between now and when such a crash takes place.
So rather than trying to crush it from a financial apocalypse, I’ve become much more interested in finding investments that might survive one. I increasingly look at the world through the lens of Austrian economics, sound money, and the possibility that the financial system we’ve built is considerably more fragile than most people appreciate.
Lately I’m looking for the cockroaches of the investing world: fundamentally sound businesses and assets that are so durable, so necessary, and in some cases so spectacularly boring that they might be able to withstand just about anything. Companies with real cash flows, manageable debt, durable demand, and businesses that don’t depend on perpetually cheap money or the next speculative mania to justify their existence. That doesn’t mean their stock prices would be immune to a collapse, of course. But there’s a difference between something that gets temporarily repriced in a crisis and something that drifts away with the wind when the music stops…like, for example, fartcoin.
I suppose that’s the strange place I’ve arrived at after all these years. I still have the same concerns about the monetary system, the Federal Reserve, and the direction of the country that I’ve been writing about for years. I’m just trying to express those convictions in a way that doesn’t require me to correctly predict the timing of the next catastrophe…and the ensuing policy response.
Instead of betting that everything falls apart, I’d rather spend my time finding things worth owning if it does, and ideally things that can do perfectly well if it doesn’t. It’s slightly less exciting, perhaps, but I’m running out of hair anyways. It is, to the best of what I can figure out, the most sensible way to reconcile what I believe about the world with the practical business of living in it.
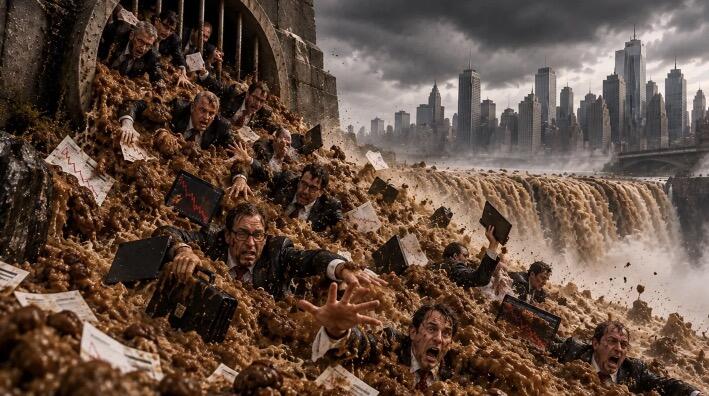
Writing is cathartic for me. It always has been. I enjoy the research, the analysis, the investigative side of things, and the process of taking a collection of seemingly unrelated observations and trying to turn them into something that makes sense. I enjoy the occasional (read: daily) opportunity to point out who and what I find to be full of sh*t. And the finance world happens to provide an inexhaustible supply of this material, like some type of sewage pump of jargon-filled bilge sitting atop of Niagara Falls. Except the sh*t smells worse than sh*t. It smells like like Davidoff Cool Water.
And of course, there’s also the mundane reality that I want to make a living. I have responsibilities and unfortunately nobody has yet offered to pay my rent in exchange for a curse-laden rant of Federal Reserve policy while sitting outside on Stone Street. So yes, I charge for some of my writing. I don’t find that embarrassing, nor do I think earning a living from financial commentary necessarily makes the commentary less valuable. The question, I suppose, is whether I’m offering something worth the reader’s time and money.
There is an extraordinary amount of terrible financial commentary out there.
There are people selling certainty about things that I believe are inherently uncertain, people who routinely underperform the indexes yet but get tons of TV time and of course people whose entire motivation for showing up to financial conferences is to try and get on the “group tab” at various bars before ducking out the side door and going back to the pool to drink Coronas with Sang Lucci.
There are also plenty of genuinely thoughtful people doing good work, often without much fanfare. The difficulty is that all of them occupy roughly the same space, competing for the same limited supply of attention.
If I wanted to bitch and moan, I could probably spend an entire article complaining about people who subscribe to Fringe Finance and then mysteriously discover a sudden interest in writing about the same ideas, or people who accuse me of “stealing” their ideas when I’ve never read anything they’ve ever written. But, really…who gives a sh*t? We’re all borrowing ideas from somewhere. Nobody develops their understanding of the world in a vacuum, and the notion that any one investor or writer has some completely proprietary window into reality strikes me as a little absurd.
I read other people’s work constantly. I listen to podcasts, read filings, follow people I agree with and people I think are completely out of their minds. Sometimes an idea comes from a conversation, sometimes from a headline, sometimes from a financial statement, and sometimes from something somebody says that irritates me enough to spend three hours trying to figure out why I think they’re wrong.
The entire financial information universe is one enormous, messy, ongoing conversation. Substack, X, Seeking Alpha, podcasts, paid newsletters, free newsletters, institutional research, mainstream financial media, and whatever some cracked out lunatic crypto scammer is posting at three in the morning are all contributing to the same enormous pool of ideas. Some of it is brilliant, some of it is nonsense, and some of it is just the same handful of observations being recycled in different packaging.
The value, somewhere inside of all of this financial detritus, appears to be in learning how to sort through the noise, recognize something worth thinking about, and occasionally stumble across an idea that changes the way you see things. Maybe that leads to an investment or leads you to avoid one. Maybe it simply makes you a little more curious about something you hadn’t previously considered. And sometimes there’s value in reading something simply because it’s interesting or entertaining, without feeling compelled to do anything with it afterward.
That’s more or less where I hope my work fits in.
I always think of that Tony Robbins movie I Am Not Your Guru from a while back. I don’t want to be anybody’s guru. And I certainly don’t want people blindly buying things because I mention them. I’d much rather be one of the many voices somebody considers while trying to develop their own understanding of markets. If something I write sends a reader down a research rabbit hole, causes them to question a popular narrative, or gives them a different way of thinking about risk, I consider that worthwhile. If they just enjoy reading it over coffee and get a laugh out of it, that’s fine with me too.
There’s a certain freedom for me in approaching writing this way. Not every observation needs to become a bull case on a stock. Not every interesting company needs to be bought. Not every macroeconomic concern needs to be expressed through some elaborate options trade that requires the world to end by the third Friday of next month. Sometimes an idea can simply exist as an idea, to be revisited later or discarded as circumstances change. I’ve found that this is a much more enjoyable way to engage with markets than constantly feeling obligated to act on everything I think.
🔥 85% OFF FOREVER IF YOU SUBSCRIBE TODAY: I am again offering an 85% discount to anyone that wants to become a Fringe Finance annual subscriber today. It’s a discount you can keep and stays applied for as long as you wish to remain a subscriber: Get 85% off forever
None of this is to suggest that I don’t take finance seriously. I do. I have plenty of opinions and plenty of convictions about where things may be heading. But I’ve become more comfortable separating the act of thinking about markets from the act of trying to make money from every thought.
There’s also the simple fact that I enjoy having a record of what I thought and when I thought it. Some of that record makes me look reasonably intelligent. Other parts make me wonder if I shouldn’t be leaving the house at all without wearing a prescription safety helmet. But that’s the nature of trying to understand something as complicated as markets in real time. You’re going to be wrong, sometimes embarrassingly so, and the only alternative is to avoid saying anything meaningful in the first place. I’ve never found that alternative particularly appealing.
I don’t think writing about investing and being good at investing are necessarily the same profession. They overlap, obviously, but they draw on different skills, different temperaments, and different motivations. There are extraordinary investors who couldn’t write an interesting paragraph to save their lives, and there are excellent financial writers whose greatest contribution may be helping other people think more clearly rather than generating spectacular returns themselves. I don’t think there’s anything inherently wrong with either arrangement, provided everyone is reasonably candid about what they’re offering.
For me, this publication is a combination of things. It’s a business, certainly, but it’s also an outlet, a place to organize my thoughts, an excuse to keep learning, and a way to participate in a conversation I’ve been fascinated by for most of my adult life. It gives me a reason to get up every morning and try to understand something a little better than I did the day before. And every so often, if I’m lucky, I might write something that helps somebody else do the same. Sometimes I get comments from subscribers that angrily proclaim something like “I’m here for the analysis, not a diatribe about whatever is on your mind at any given second!”
And all I can think is boy, are you in the wrong f**king place…
I don’t know that there’s a more complicated explanation than that, and I’m not sure there needs to be.
So, returning to the question that started all of this, why don’t I just keep my investment ideas to myself and make a fortune trading them?
Partly because I’ve tried that, and the results have left something to be desired. Partly because I genuinely enjoy the process of writing. Partly because I think there’s room for independent commentary that doesn’t bullshit people into making them think I know exactly what happens next. And partly because I’ve come to appreciate that an idea doesn’t have to make somebody rich to have been worth thinking about.
I think there’s a place for that in a world increasingly obsessed with gambling on literally everything, immediate results, instant opinions, and turning every passing thought into a transaction.
At the end of the day, I’m just trying to make a living doing something I enjoy, share a few ideas I find interesting, and hopefully offer something useful along the way. Some days that means finding a potential opportunity. And some days it means writing a couple thousand words about a question nobody ever asked me…like today.
Thanks, as always, for reading.
—
QTR’s Disclaimer: Please read my full legal disclaimer on my About page here.
Tyler Durden
Tue, 10/13/2026 – 10:25
ZeroHedge News
[crypto-donation-box type=”tabular” show-coin=”all”]